Public Health Regulation and the Limits of Investment Protection: When investment protection meets public health regulation
Philip Morris Brands Sàrl, Philip Morris Products S.A. and Abal Hermanos S.A. v Oriental Republic of Uruguay (ICSID Case No ARB/10/7), Award, 8 July 2016.
Philip Morris v Uruguay concerned Uruguay’s tobacco-control legislation and became one of the leading investment arbitration decisions concerning the State’s right to regulate for public health.1
The Dispute:
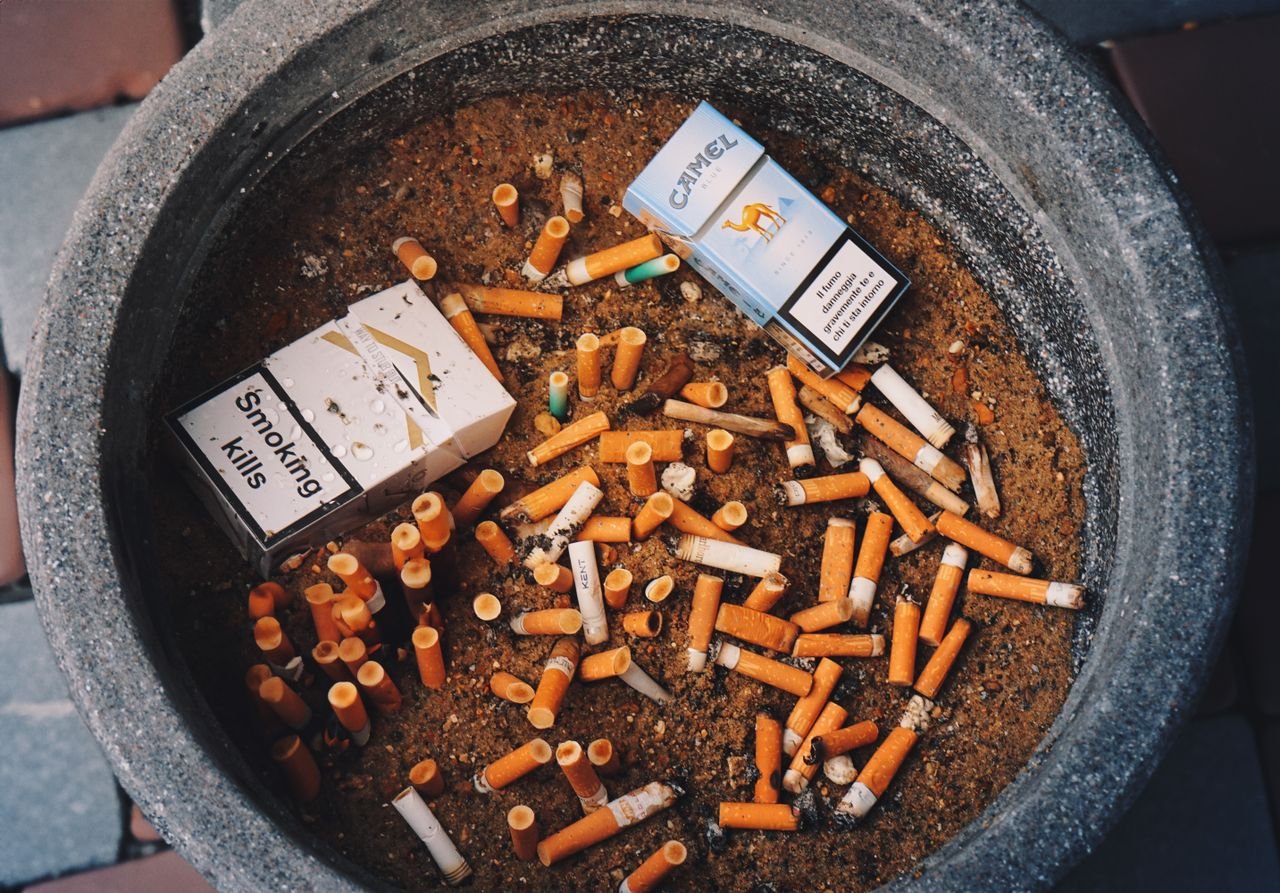
The dispute arose after Uruguay introduced two tobacco-control measures. The first, known as the Single Presentation Regulation, restricted tobacco manufacturers to a single presentation of each cigarette brand. The second, commonly referred to as the 80/80 Regulation, increased the proportion of cigarette packaging required to carry health warnings from 50 per cent to 80 per cent.2
Philip Morris argued that the measures interfered with its trademarks and substantially reduced the value of its investments in Uruguay. It brought claims under the Switzerland–Uruguay BIT, including claims relating to expropriation and fair and equitable treatment.3
A central question was whether the regulatory measures constituted an unlawful expropriation. The Tribunal examined the measures against the background of the State’s police powers. It recognised that States retain regulatory authority to protect public welfare and that a bona fide, non-discriminatory regulation adopted for a public purpose will not necessarily constitute compensable expropriation.4
The Tribunal Decision:
The Tribunal concluded that the measures were adopted in pursuit of legitimate public-health objectives. Importantly, it did not require Uruguay to establish that the measures were capable of producing a demonstrable health effect in isolation from the country’s wider tobacco-control programme. Instead, the Tribunal considered whether the measures were directed towards the public-health objective and were capable of contributing to its achievement.5
The Tribunal therefore rejected Philip Morris’s expropriation claim. It similarly rejected the claim that Uruguay had violated the fair and equitable treatment standard. The Tribunal considered the measures to be a legitimate exercise of Uruguay’s regulatory authority and found no basis for concluding that the State had acted arbitrarily or discriminatorily.6
The case is significant because it illustrates that investment protection does not necessarily freeze a State’s regulatory framework at the moment an investment is made. The Tribunal expressly recognised that States must retain regulatory flexibility, particularly in areas such as public health.7
Why the case matters
The case is also significant from a procedural participation perspective. Given the public interest involved, the Tribunal permitted the World Health Organization (WHO) and the Secretariat of the WHO Framework Convention on Tobacco Control (WHO FCTC) to submit a joint amicus curiae brief, while the Pan American Health Organization (PAHO) made a separate submission. The Tribunal considered that these submissions could provide an independent perspective and relevant expertise, and subsequently relied on the WHO/FCTC submission at several points in its analysis.
The case therefore illustrates how investment arbitration can accommodate perspectives beyond those of the investor and the State, while also highlighting the limited and discretionary nature of such participation: the organisations were not parties to the dispute and did not acquire the procedural position of the disputing parties.
Philip Morris v Uruguay is now regularly examined alongside disputes involving environmental protection, climate regulation and other forms of public-interest regulation. Its importance is not that States have an unlimited regulatory power; rather, the case demonstrates how tribunals may distinguish legitimate regulation from measures that cross the threshold into treaty breach.
For investment governance, the case raises a broader question: how should investment law protect investors while preserving sufficient regulatory space for States to respond to evolving public-interest priorities?
The Tribunal dismissed all of the claimants’ claims and ordered them to bear 70 per cent of Uruguay’s legal costs and expenses.
Explore other case files:
Leave a Reply