Communities affected by investment projects: who decides the rules, who holds the power, and who bears the consequences?
When an investment project arrives, whether a dam, a mine, a highway, or a technology park, it rarely presents itself as a political act. It comes wrapped in the language of development, growth, and inevitability. Capital flows. Jobs ware created. Infrastructure unlocks the full potential. But behind every investment is a set of rules, and behind those rules is power.
The most important question we rarely ask is not whether investment is good or bad, the question is:
Who gets to decide the terms under which it happens?Who bears the consequences when it goes wrong?
Investment law is often described as technical, specialised, even neutral. Treaties, contracts, and arbitration clauses are framed as instruments designed to provide certainty and reduce risk. Politics, we are told, belongs elsewhere.
Rules that govern cross-border investment are not neutral. They are negotiated, drafted, and enforced in ways that reflect particular interests, priorities, and assumptions about whose risks matter most. They protect capital from instability, but they do far less to protect the people most affected by supported projects.
What looks like “legal certainty” from one angle often appears as democratic distance from another. Decisions that reshape land use, water access, labour markets, and local economies are frequently made far from the communities most affected by them, sometimes thousands of kilometres away, in treaty negotiations or arbitration rooms closed to the public.
Therefore, the law does not merely organise investment. It structures power around it.
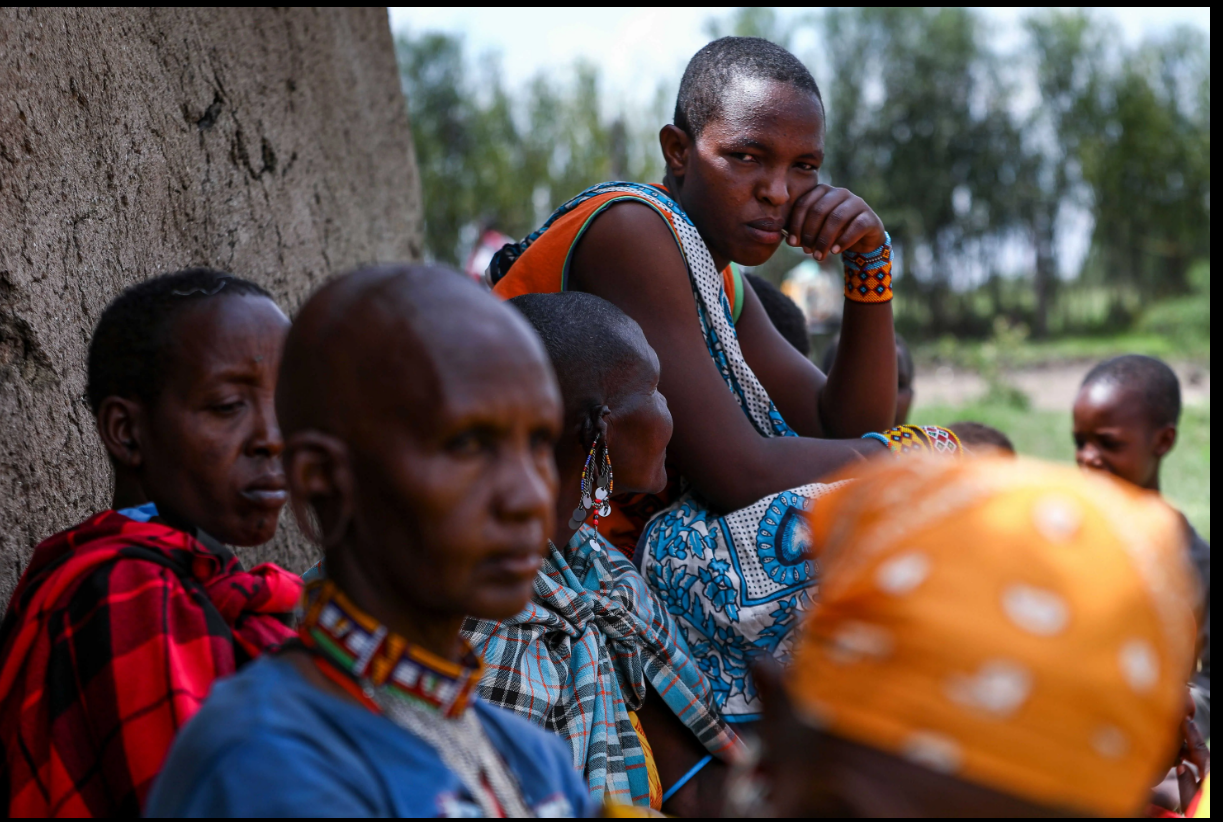
For communities, this matters deeply. Investment projects affect land, livelihoods, cultural practices, and ecological systems. Yet communities are neither recognised as participants in the legal architecture that governs these projects nor as parties to the adjudication processes resolving the disputes. At best, they are “consulted.” At worst, they are treated as obstacles to be managed.
The result is a familiar pattern: benefits are projected at the national or global level, while harms are experienced locally. When communities resist, they are often framed as “anti-development,” “irrational”, or “misinformed,” rather than as actors responding to decisions made without their meaningful involvement.
Where conflict really comes from
Investment-related conflict is frequently explained as a failure of governance, attributed to weak institutions, poor implementation, corruption, or insufficient capacity. While these factors matter, they do not tell the whole story. Conflict often emerges because the sites of decision-making, benefit, harm, and accountability do not align.
This is because:
Decisions are made internationally or centrally.
Profits flow to investors and, sometimes, state treasuries.
Social and environmental costs are borne locally.
Disputes are resolved in forums inaccessible to affected communities.
Under these conditions, conflict is not an anomaly. It is predictable.
When communities protest, litigate, or mobilise politically, they are not rejecting law; they are contesting a legal order that excludes them.
Yet the dominant dispute-resolution mechanisms in investment law are primarily designed to address conflicts between investors and states, not between investment projects and communities.
This is a structural mismatch. We attempt to resolve deeply social and political disputes using tools designed to protect economic expectations.
How those disputes are later resolved reveals the full implications of this design. The question we need to sit with is:
Who designs these rules? Whose risks do they prioritise, and whose claims do they render peripheral?
This is not an argument against investment. Nor is it a call to romanticise resistance or reject legal order. It is a call to be honest about how rules work and for whom.
Investment law does not simply respond to economic reality. It constructs it. It allocates risk, stabilises expectations, and defines whose interests warrant insulation from change. If investment reshapes governance, then the rules that structure it are not technical instruments; they are political decisions about power.
Everything else, participation, conflict, and resolution, follows from that architecture.
Explore related resources:
Other Resources related to the article:
| Source | Relates to |
|---|---|
| UNCTAD – International Investment Agreements | Investment treaties, investment governance, reform of the international investment regime |
| ICSID – About ICSID / ISDS | Investor–State dispute settlement and arbitration architecture |
| OECD – Responsible Business Conduct | Investment, affected communities, environmental/social impacts and responsible investment |
| World Bank – Environmental and Social Framework | Community participation, consultation, displacement and project impacts |
| OHCHR – Business and Human Rights | Human rights implications of investment and business activity |
| UN Working Group on Business and Human Rights | Corporate responsibility, affected communities and access to remedy |
| UNCITRAL – Transparency in Treaty-based Investor-State Arbitration | Transparency/public participation in ISDS |
| International Labour Organization | Labour impacts of investment and development projects |