How East African investment governance is structured across national investment authorities, entry mechanisms, regulatory oversight and strategic investment frameworks.
Who Governs Investments in Kenya, Uganda and Tanzania?
Investment law often speaks about “the State” as though it were a unified legal personality.
Investment governance is anything but unified. Behind a major investment project may sit an investment promotion authority, a ministry, a sector regulator, an environmental authority, a land administration body, a tax authority, a local government, a public procurement institution and, in some cases, a state-owned enterprise.
The investor encounters these institutions as a regulatory system. The community encounters them as the State. This difference matters. If investment governance is fragmented across institutions, accountability can become fragmented too. Kenya, Uganda and Tanzania provide useful examples of how East African states have attempted to coordinate these competing institutional functions.
Kenya
Kenya: A network rather than a single investment regulator
Kenya’s investment architecture is decentralised across a number of institutions. KenInvest has a central promotional and facilitative mandate, but it does not replace sectoral regulators. The Investment Promotion Act gives KenInvest responsibility for promoting and facilitating investment, including assisting investors to obtain licences, permits and incentives.[1] This creates an important institutional distinction.
KenInvest can help an investor navigate the regulatory system, but the authority to regulate the underlying activity may remain with another public institution. An energy project, for example, can involve investment promotion, environmental regulation, land administration, energy regulation, county-level approvals and potentially public procurement or PPP institutions. This means that the investor’s legal relationship with the state is multi-institutional.
The 2024 U.S. Investment Climate Statement on Kenya recognised both the increasing digitisation of regulatory processes and continuing complaints concerning bureaucratic delays and discretionary administrative powers.[2]This tension is central to investment governance.
Digitisation can make procedures more accessible without necessarily resolving the underlying question of who exercises substantive regulatory discretion.Kenya’s constitutional framework adds another layer. Public participation is constitutionally embedded in government decision-making, while legislation governing areas such as environmental management, land, public finance and administrative action contains additional participatory or procedural requirements.[3]
The institutional question is therefore not merely:
Which institution promotes investment?
It is:
Which institution is responsible for each stage of the investment’s life cycle and how are those institutions coordinated?
Uganda
Uganda: The one-stop centre as institutional coordination
Uganda has pursued a more explicit coordination model. The Investment Code Act 2019 designates UIA as a one-stop centre for investment coordination, promotion, facilitation, monitoring and evaluation.[4] This is conceptually significant. A one-stop centre attempts to solve a familiar problem in investment governance: institutional fragmentation creates transaction costs.
Rather than requiring an investor to independently navigate multiple public bodies, the state attempts to coordinate the regulatory process around a central institution.
Uganda has continued to develop this model digitally. UIA currently describes its one-stop centre as bringing together numerous government agencies dealing with company registration, taxation, immigration, environmental clearance, land verification, standards, utilities, social security and other services.[5]
The institutional architecture therefore seeks to convert a collection of regulatory agencies into a coordinated service system. But coordination is not the same thing as consolidation.The agencies do not necessarily lose their statutory mandates merely because they are physically or digitally coordinated. This distinction is critical. That is a strength when institutional expertise must be preserved.
A one-stop centre can make government easier to navigate without eliminating the substantive independence of the environmental authority, tax authority, land authority or sector regulator.
It becomes a weakness when coordination is treated as a substitute for accountability.
Uganda
Central coordination through the National Investment Steering Committee
Tanzania’s 2022 investment framework takes institutional coordination further. The Tanzania Investment Act establishes TIC as the primary government agency for coordinating, encouraging, promoting and facilitating investment.[6] But the Act also creates a National Investment Steering Committee composed of senior government officials across multiple areas of government.[7]
Its membership includes the Prime Minister, Attorney General, ministers responsible for investment, finance and lands, the Governor of the Bank of Tanzania, the Commissioner General of the Tanzania Revenue Authority and the Executive Director of TIC, among others.This is not merely an administrative convenience. It is an attempt to bring multiple state interests into the governance of investment.
The Committee is responsible for providing leadership on investment policy, approving incentives for strategic and special strategic investors and providing oversight for large projects with significant national impact.[8]
This architecture recognises something that investment law sometimes obscures:
investment governance is inherently cross-sectoral.
A large investment can simultaneously be:
- an economic project;
- a land transaction;
- an environmental intervention;
- an employment project;
- a tax matter;
- an infrastructure project;
- a foreign-exchange issue;
- and a potential source of social conflict.
No single regulator possesses all the necessary expertise.
The Institutional Paradox
At first glance, greater institutional coordination appears unquestionably desirable.
But coordination creates a paradox. The more the state tries to create a seamless investment environment, the easier it may become for the investor to navigate government. That is beneficial for investment facilitation.Yet from an accountability perspective, the same seamlessness can make it harder to identify where responsibility lies when something goes wrong.
Example:
Consider a hypothetical infrastructure project.
If the project subsequently causes serious harm, who is accountable?
The answer cannot simply be “the government”. Institutional accountability requires identifying:
who made the decision;
who supplied the information;
who assessed the risk;
who approved the activity;
who monitored compliance;
who received complaints; and
who possessed legal power to intervene.
This is where institutional design becomes a substantive investment-governance question.
Regulatory authority and the problem of capacity
Institutional design also cannot be separated from institutional capacity. A regulator may possess extensive statutory powers while lacking sufficient personnel, expertise, information or financial resources to exercise them effectively.This distinction is particularly important in developing investment economies.
Uganda’s 2022 IMF Public Investment Management Assessment found significant improvements in institutional design but also observed that several reforms remained relatively recent and were not yet fully institutionalised.[9]
Tanzania’s IMF governance assessment similarly noted that while its legal and institutional framework was comparatively developed in several respects, implementation and enforcement could still be strengthened.[10]
These observations reveal an important distinction:
Legal authority is not the same as regulatory capacity.
A regulator may legally be empowered to monitor an investment while being practically incapable of doing so. The result is a form of formal regulation without effective oversight.
Who regulates the regulator?
There is another institutional question that receives less attention.
Who oversees the bodies responsible for facilitating and regulating investment?
Investment authorities have a structural incentive to attract and retain investment. Sector regulators may have a different mandate. Environmental authorities may prioritise ecological protection. Local governments may prioritise community interests and local development. Tax authorities seek revenue. Central government may prioritise national economic growth. These interests can conflict.
A mature investment governance framework therefore needs mechanisms that prevent one institutional objective, particularly investment attraction, from overwhelming other legitimate public objectives.
A project classified as strategically important may receive greater political attention precisely because of its anticipated economic benefits but strategic importance should arguably generate greater scrutiny, not less.
Institutions Roles in Decision Making
Institutional architecture also determines whose knowledge counts. Investors typically possess technical, financial and legal expertise. Government agencies possess administrative and regulatory expertise. Communities may possess something different: They may know how land is actually used, where water sources are located, how grazing routes operate or how a proposed project may affect livelihoods
If the institutional structure does not provide a meaningful channel through which this knowledge enters the regulatory process, the resulting decision may be legally valid while remaining substantively incomplete. This is where investment governance intersects directly with procedural justice.
So the question is not simply whether communities are “consulted”. It is whether the institutional structure gives their information the capacity to influence the decision.
Conclusion
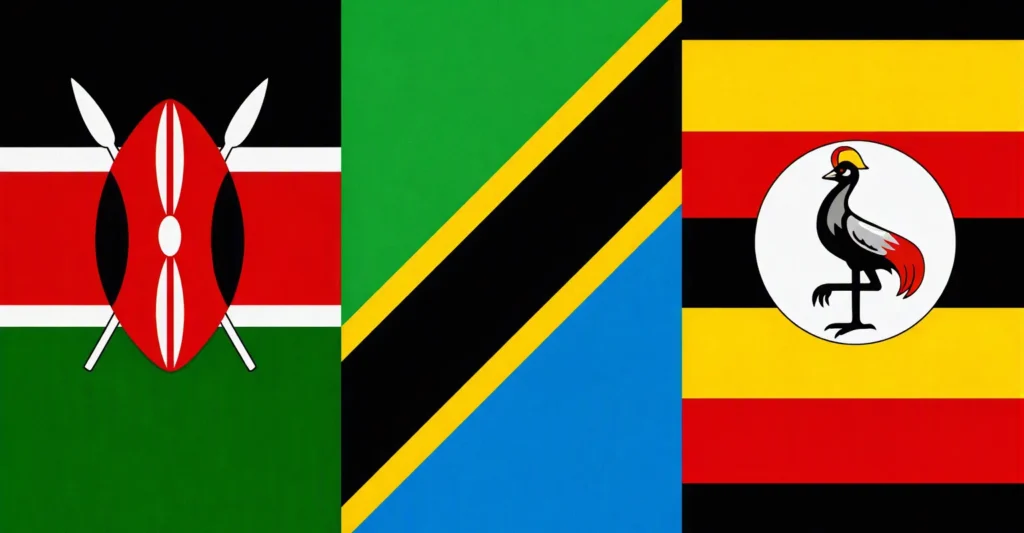
Kenya, Uganda and Tanzania demonstrate three approaches to institutional coordination.
Kenya relies heavily on a network of investment and sectoral institutions. Uganda has placed substantial emphasis on the one-stop-centre model. Tanzania’s 2022 legislation has combined a central investment institution with a high-level National Investment Steering Committee.
None of these models eliminates the underlying institutional problem. Investment governance is inherently multi-actor.
The challenge is therefore not to create one institution capable of doing everything. It is to create clear lines of authority, coordination, information-sharing, monitoring and accountability between institutions.
The most important question may consequently not be:
Who governs investment?
It may be:
How does the state govern itself when multiple public institutions have legitimate but competing interests in the same investment?
That is where investment governance becomes more than investment promotion. It becomes a question of public power.
FOOTNOTES
[1] Investment Promotion Act 2004 (Kenya), s 15. (Investment Policy Hub)
[2] U.S. Department of State, 2024 Investment Climate Statement: Kenya. (State.gov)
[3] See discussion of Kenya’s constitutional and statutory public participation requirements in the U.S. Department of State’s investment-climate analysis. (State.gov)
[4] Investment Code Act 2019 (Uganda). (Investment Policy Hub)
[5] Uganda Investment Authority, current One Stop Centre description. (Uganda Investment Authority)
[6] Tanzania Investment Act 2022, s 4. (Investment Policy Hub)
[7] Tanzania Investment Act 2022, s 5. (Investment Policy Hub)
[8] Ibid.
[9] IMF, Uganda: Technical Report—Public Investment Management Assessment, IMF Staff Country Report No 22/350 (2022). (IMF eLibrary)
[10] IMF, United Republic of Tanzania: 2023 Article IV Consultation, IMF Country Report No 23/153 (2023). (IMF eLibrary)
Leave a Reply